The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may…
⏱ 6 min read
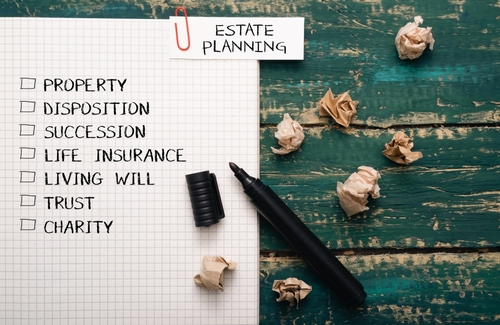
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Heirless Estate Planning
October 1, 2026 · Blog, Financial Planning, Uncategorized
⏱ 6 min read
The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.
Without a formal will, the general rule for inheritance distribution starts with a surviving spouse and children (who often share the estate), followed by grandchildren, parents, siblings, nephews and nieces, grandparents, then other extended relatives such as aunts, uncles and cousins. The exact order varies by state. Note that ex-spouses, and in most states stepchildren, receive nothing under standard state inheritance laws; they must be specified in a will or trust document, or named as an account beneficiary, to receive any consideration.
This means that, without a will or close family heir, your assets could go to an estranged sibling or even a cousin you’ve never met. If you have absolutely no family left when you pass on, the proceeds generally go to the state through a process called escheat (this includes funds from physical assets that are auctioned off).
Start with Living Matters
Before you start allocating where your assets go after your death, first complete paperwork assigning people to manage your assets if you ever become incapacitated while still alive. The key documents include:
Durable Power of Attorney (DPOA) – this document names an agent, such as a trusted friend, attorney, or bank trust department, to take over managing your financial and legal affairs if you are deemed unable.
Health Care Directive – authorizes someone to make medical decisions on your behalf when you are unable.
Living Will – details what life-saving procedures and treatments you would and would not like to receive in order to keep you alive. Separately, a DNR (do not resuscitate) order, signed by your physician, directs medical staff not to perform CPR if your heart or breathing stops.
Choose Your Estate Manager
Your will should assign an executor to manage your estate once you pass away. Again, this can be a friend or a custodian (e.g., bank, attorney, financial advisor). This person is responsible for initiating probate court proceedings and distributing assets as dictated by your will. Responsibilities may include notifying your landlord/lender(s), utility providers, banks, credit card companies, investments, and insurance companies of your passing, as well as managing the sale of any property you own. Most states allow any competent adult to serve as executor, including the attorney who drafted your will, though some states restrict people with felony convictions or those who live out of state.
It behooves the heirless to consider estate planning to better allocate funds toward people or causes they care about, such as friends, coworkers, or charities. For example:
Animal shelter or humane society
Local church or other religious institution
The public library
The Public Broadcasting Service (PBS)
A local land trust, the World Wildlife Fund or other conservation organizations
A favorite city institution, such as a museum, zoo, symphony, ballet or theater
Scholarship fund for your alma mater – K-12 or university
YMCA or Jewish community center
Medical institutions, such as local clinics, St. Jude Children’s Research Hospital, Planned Parenthood, cancer or other disease research
Charities for children, such as the National Center for Missing & Exploited Children or Children’s Health Fund
If nothing local appeals, browse options at websites such as CharityWatch.org, a website dedicated to assessing how efficiently charities use donations.
Note that retirement accounts and life insurance policies generally request a beneficiary, and many bank and brokerage accounts allow one. You may not even remember that when you opened an account years ago, you listed your boyfriend or wife at the time as your beneficiary, even though that person is now your ex. Be aware that these beneficiary designations supersede any will instructions. These assets pass directly to the named beneficiary outside of probate, without going through your executor. Be sure to check and confirm your beneficiary designations while you are still alive to eliminate this issue. Many states automatically revoke an ex-spouse’s designation after a divorce, but that rule generally does not apply to employer retirement plans such as 401(k)s, so an ex could still collect. If no beneficiary is named, the account typically becomes part of your estate and goes through probate.
Charitable Donations
For people with substantial assets who want to leave money to one or more charities, sophisticated philanthropic vehicles include:
Charitable remainder trust – The money is deposited into a trust while you are still alive. You receive an immediate tax deduction based on the present value of the charity’s future share (the remainder interest) of this irrevocable trust, as well as an income stream from the trust for life or for a set term of up to 20 years. When the trust ends, whatever charity you designate receives the remaining assets.
Donor-advised funds – You make an irrevocable, tax-deductible contribution of cash, securities, or appreciated noncash assets to a fund, which is professionally managed for future growth. You may recommend money be granted to a qualified 501(c)(3) charity over time, basically leaving a legacy that continues to give.
Private foundations – You can actually start your own charitable organization with an initial tax-deductible gift and appoint a board of directors or trustees (who may receive reasonable compensation) to manage and distribute assets according to your wishes. Foundations can make grants beyond public charities in limited cases, but only under strict IRS rules. They must also distribute at least 5 percent of their assets each year and pay an excise tax on investment income, and donors face lower deduction limits than for gifts to public charities.
It is best to consult with a financial advisor, tax professional, or estate planning attorney with experience in setting up a sophisticated charitable giving plan to make the most of your contributions.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later…
⏱ 4 min read
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
The IRS is finally doing something about it. Notice 2026-49 puts out four sample forms and a five-step procedure meant to bring some consistency to direct rollovers. Plans do not have to use them, and there is no safe harbor, but you can see where this is going.
The Problem Worth Solving
When you leave a job, you have to figure out what to do with your 401(k). You can cash it out and take the tax hit. You can leave it sitting there. Or you can roll it into a new employer’s plan or an IRA.
A direct rollover is usually the way to go. The money travels straight from the old plan to the new one without ever hitting your bank account, which keeps things clean and avoids the 60-day deadline you face if you take possession yourself.
The trouble is that every plan does things differently. A 2024 GAO study found that roughly one in three people doing rollovers ended up with a paper check in hand that they were supposed to forward themselves. Checks get lost. They sit on the counter for weeks. And the whole time, that money is not invested anywhere.
How the New System Works
Here is what Treasury is proposing. You fill out Form 1 and give it to the plan or IRA that will be receiving your money. That form lets the receiving plan reach out to your old plan and handle the transfer on your behalf. The two plans swap Forms 2 through 4 to make sure everything is in order. If something goes sideways, the receiving plan has to tell you.
The IRS wants this done electronically whenever possible. When electronic is not an option, the old plan should write a check payable to the receiving plan for your benefit and mail it directly there. No more sending checks to participants and hoping they take it from there.
Tax Rules Stay the Same
None of this changes how rollovers are taxed. Eligible distributions that complete a proper rollover still stay out of income. You still cannot roll over a required minimum distribution. Pre-tax money stays pre-tax. Roth stays Roth. This is about the plumbing, not the tax code.
IRA-to-IRA transfers are not covered here. Those already go through the ACATS electronic system, so Treasury left them alone.
No Safe Harbor Yet
Plans can use these forms, change them, or ignore them completely. Right now, there is no reward for following along.
That could change. Treasury says it is thinking about offering safe harbors down the road. A receiving plan that uses the standard forms might eventually be allowed to assume the rollover is valid unless something looks off. That would give administrators a real incentive to adopt the new process.
Conclusion and What Comes Next
The IRS has hinted at bigger changes. Future guidance might require electronic transfers across the board, kill off the practice of mailing checks to participants, and get rid of some of the procedural friction that slows things down.
For now, the sample forms are sitting in the appendix of Notice 2026-49. They are there if you want them. If you have ever spent weeks tracking down a check that went to the wrong address or trying to explain one plan’s process to another plan’s administrator, you understand what Treasury is trying to fix. They want rollovers to be faster, simpler, and harder to mess up. This is a start.
Rolling Over Your 401(k) Just Got Less Painful – Here’s What the IRS Changed
October 1, 2026 · Blog, Tax and Financial News, Uncategorized
⏱ 4 min read
Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
The IRS is finally doing something about it. Notice 2026-49 puts out four sample forms and a five-step procedure meant to bring some consistency to direct rollovers. Plans do not have to use them, and there is no safe harbor, but you can see where this is going.
The Problem Worth Solving
When you leave a job, you have to figure out what to do with your 401(k). You can cash it out and take the tax hit. You can leave it sitting there. Or you can roll it into a new employer’s plan or an IRA.
A direct rollover is usually the way to go. The money travels straight from the old plan to the new one without ever hitting your bank account, which keeps things clean and avoids the 60-day deadline you face if you take possession yourself.
The trouble is that every plan does things differently. A 2024 GAO study found that roughly one in three people doing rollovers ended up with a paper check in hand that they were supposed to forward themselves. Checks get lost. They sit on the counter for weeks. And the whole time, that money is not invested anywhere.
How the New System Works
Here is what Treasury is proposing. You fill out Form 1 and give it to the plan or IRA that will be receiving your money. That form lets the receiving plan reach out to your old plan and handle the transfer on your behalf. The two plans swap Forms 2 through 4 to make sure everything is in order. If something goes sideways, the receiving plan has to tell you.
The IRS wants this done electronically whenever possible. When electronic is not an option, the old plan should write a check payable to the receiving plan for your benefit and mail it directly there. No more sending checks to participants and hoping they take it from there.
Tax Rules Stay the Same
None of this changes how rollovers are taxed. Eligible distributions that complete a proper rollover still stay out of income. You still cannot roll over a required minimum distribution. Pre-tax money stays pre-tax. Roth stays Roth. This is about the plumbing, not the tax code.
IRA-to-IRA transfers are not covered here. Those already go through the ACATS electronic system, so Treasury left them alone.
No Safe Harbor Yet
Plans can use these forms, change them, or ignore them completely. Right now, there is no reward for following along.
That could change. Treasury says it is thinking about offering safe harbors down the road. A receiving plan that uses the standard forms might eventually be allowed to assume the rollover is valid unless something looks off. That would give administrators a real incentive to adopt the new process.
Conclusion and What Comes Next
The IRS has hinted at bigger changes. Future guidance might require electronic transfers across the board, kill off the practice of mailing checks to participants, and get rid of some of the procedural friction that slows things down.
For now, the sample forms are sitting in the appendix of Notice 2026-49. They are there if you want them. If you have ever spent weeks tracking down a check that went to the wrong address or trying to explain one plan’s process to another plan’s administrator, you understand what Treasury is trying to fix. They want rollovers to be faster, simpler, and harder to mess up. This is a start.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Temps are dropping, the leaves are turning and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are…
⏱ 3 min read
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
How to Save Energy This Fall
October 1, 2026 · Blog, Tip of the Month, Uncategorized
⏱ 3 min read
Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
Fix stuff around your house. These are simple and might require a little elbow grease on your part, but they’re well worth it because they help your house stay warmer, eliminate drafts, and help your heater work more efficiently.
Seal gaps around your windows and doors with caulk or weatherstripping.
Close fireplace dampers when you’re not using them.
Replace HVAC filters. For your furnace, this should be done one to three months before cold weather hits. It helps improve air quality (and air flow) inside your home.
Add door sweeps to exterior doors.
Reverse your ceiling fans; set them to clockwise and put them on a low setting to push the warm air down into the room.
Hang thick(er) curtains so heat doesn’t seep out.
Make sure vents and returns aren’t blocked by furniture or rugs.
Check your heating system. Before the Arctic blast arrives, these tasks are key:
Schedule an HVAC inspection – aka a tune-up.
Install a programmable or smart thermostat.
Lower your thermostat by 7-10 degrees when you’re away.
Look at your insulation. These chores might require you to hire someone.
Add attic insulation if your house is under-insulated so you can reduce your heating costs and keep your house toasty. (In fact, poor insulation is one of the biggest sources of energy loss.)
Insulate pipes that are exposed, as well as your water heater.
Seal and insulate all your ductwork in your attic, garage, and crawl spaces.
Inspect your water heater. Making sure you have warm water in the cooler months is critical. You’ll be quite happy not having to take cold showers, as well as not expending as much energy.
Lower your water heater temperature to 120°F.
Install low-flow showerheads.
Fix dripping faucets immediately.
Examine the exterior of your house. Even the outside of your home needs attention.
Clean gutters and downspouts to prevent ice dams, moisture problems, and foundation issues.
Trim branches that could block winter sunlight from south-facing windows.
Check for cracks where utilities enter the house and seal them.
Check your roof, too, for signs of wear or damage.
Test your heating system early. Put this on your calendar! Don’t wait until it’s a tundra outside to turn on your furnace or heat pump.
If you need repairs, schedule maintenance before HVAC companies get all booked up.
Check your smoke and carbon monoxide detectors. Don’t leave this unattended!
Replace batteries if needed and test them all. You want to make sure your family’s safe during the upcoming heating season.
Even though fall is upon us, know this: Winter is coming, as the show famously claims. You can never be too prepared!
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed…
⏱ 4 min read
Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
Prison Staff Safety Enhancement Act (S 307) – This bill is designed to address sexual harassment and sexual assault of Bureau of Prisons correctional officers and other staff by incarcerated prisoners. Specifically, it details national standards for the prevention, reduction, and punishment of perpetrators. The legislation was introduced by Sen. Marsha Blackburn (R-TN) on Jan. 29, 2025. It passed in the Senate on April 29, 2025; in the House on Aug. 31; and was enacted by the president on Sept. 16.
Retire through Ownership Act (S 2403) – Introduced by Sen. Roger Marshall (R-KS) on July 23, 2025, this bill amends the Employee Retirement Income Security Act of 1974. ESOPs are Employee Stock Ownership Plans that enable employees to accrue shares of their employers’ stock as part of a pension plan, in which they receive the cash value of their shares upon retirement. This bill clearly defines how a good-faith valuation should be determined by independent professional appraisers, based on IRS Revenue Ruling 59-60 for valuing privately held stock. In the past, ambiguous valuation methods have resulted in litigation. This act passed in the Senate on October 9, 2025, and in the House on Sept. 16. It currently awaits the president’s signature.
Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 (HR 5334) – This largely bipartisan act was championed by the late Sen. Lindsey Graham (R-SC). The legislation imposes a variety of sanctions, tariffs, and prohibitions related to Russia and Iran, and explicitly prohibits U.S. persons from making new investments in Russia. It also expands the tax deduction for early childhood education teachers for classroom expenses. The bill was introduced on Sept. 11, 2025, by Rep. Jimmy Panetta (D-CA). It passed in the House on April 27 and in the Senate on Aug. 7, with final changes agreed upon on Sept. 16. The president signed the bill into law a day later.
Digital Asset Market Clarity Act (HR 3633) – Known as the Clarity Act, the purpose of this Trump Administration-backed bill is to implement the first regulations for the crypto sector. The bill was introduced by Rep. French Hill (R-AR) on May 29, 2025. It passed in the House on July 17, 2025. However, opponents of the bill say the industry-led standards are far too lenient and do not provide enough safeguards. The bill recently failed in the Senate after a party-line cloture vote, which means the debate ended before the floor could vote on the bill (considered a filibuster). The cloture vote does not rule out the Senate trying again at a later date.
Ratepayer Protection Act (HR 9340) – In an effort to rein in AI data center utility costs, this bill would require state utilities to consider adopting standards to ensure cost recovery for the generation, transmission, and distribution services of large-load electricity customers. This high-stakes, bipartisan issue comes ahead of the midterm elections in an effort to assure voters that local data centers will not ramp up local residents’ utility bills. The legislation was introduced by Rep. Gabe Evans (R-CO) on June 18. It passed in the House on Sept. 16 and currently resides in the Senate.
Stopping Political Discrimination in Disaster Assistance Act (HR 1342) – Current law states that federal major disaster emergency relief and assistance must be provided without discrimination on the basis of race, color, religion, nationality, sex, age, disability, English proficiency or economic status. The bill, introduced by Rep. Scott Perry (R-PA) on Feb. 13, 2025, would add political affiliation protection under this requirement. The act passed in the House on Sept. 16 and awaits consideration in the Senate.
Pre-Election Focus on Russian/Iran Sanctions, AI Utility Bills, Crypto Regulation and Nondiscriminatory FEMA Assistance
October 1, 2026 · Blog, Congress at Work, Uncategorized
⏱ 4 min read
Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
Prison Staff Safety Enhancement Act (S 307) – This bill is designed to address sexual harassment and sexual assault of Bureau of Prisons correctional officers and other staff by incarcerated prisoners. Specifically, it details national standards for the prevention, reduction, and punishment of perpetrators. The legislation was introduced by Sen. Marsha Blackburn (R-TN) on Jan. 29, 2025. It passed in the Senate on April 29, 2025; in the House on Aug. 31; and was enacted by the president on Sept. 16.
Retire through Ownership Act (S 2403) – Introduced by Sen. Roger Marshall (R-KS) on July 23, 2025, this bill amends the Employee Retirement Income Security Act of 1974. ESOPs are Employee Stock Ownership Plans that enable employees to accrue shares of their employers’ stock as part of a pension plan, in which they receive the cash value of their shares upon retirement. This bill clearly defines how a good-faith valuation should be determined by independent professional appraisers, based on IRS Revenue Ruling 59-60 for valuing privately held stock. In the past, ambiguous valuation methods have resulted in litigation. This act passed in the Senate on October 9, 2025, and in the House on Sept. 16. It currently awaits the president’s signature.
Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 (HR 5334) – This largely bipartisan act was championed by the late Sen. Lindsey Graham (R-SC). The legislation imposes a variety of sanctions, tariffs, and prohibitions related to Russia and Iran, and explicitly prohibits U.S. persons from making new investments in Russia. It also expands the tax deduction for early childhood education teachers for classroom expenses. The bill was introduced on Sept. 11, 2025, by Rep. Jimmy Panetta (D-CA). It passed in the House on April 27 and in the Senate on Aug. 7, with final changes agreed upon on Sept. 16. The president signed the bill into law a day later.
Digital Asset Market Clarity Act (HR 3633) – Known as the Clarity Act, the purpose of this Trump Administration-backed bill is to implement the first regulations for the crypto sector. The bill was introduced by Rep. French Hill (R-AR) on May 29, 2025. It passed in the House on July 17, 2025. However, opponents of the bill say the industry-led standards are far too lenient and do not provide enough safeguards. The bill recently failed in the Senate after a party-line cloture vote, which means the debate ended before the floor could vote on the bill (considered a filibuster). The cloture vote does not rule out the Senate trying again at a later date.
Ratepayer Protection Act (HR 9340) – In an effort to rein in AI data center utility costs, this bill would require state utilities to consider adopting standards to ensure cost recovery for the generation, transmission, and distribution services of large-load electricity customers. This high-stakes, bipartisan issue comes ahead of the midterm elections in an effort to assure voters that local data centers will not ramp up local residents’ utility bills. The legislation was introduced by Rep. Gabe Evans (R-CO) on June 18. It passed in the House on Sept. 16 and currently resides in the Senate.
Stopping Political Discrimination in Disaster Assistance Act (HR 1342) – Current law states that federal major disaster emergency relief and assistance must be provided without discrimination on the basis of race, color, religion, nationality, sex, age, disability, English proficiency or economic status. The bill, introduced by Rep. Scott Perry (R-PA) on Feb. 13, 2025, would add political affiliation protection under this requirement. The act passed in the House on Sept. 16 and awaits consideration in the Senate.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding…
⏱ 3 min read
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding how the Exchange Ratio works is essential for businesses and investors to maximize these processes.
The ratio assesses how many shares the company that’s purchasing the takeover company must issue per share of the takeover business. Transactions that use shares for part or whole of the payment are able to leverage this integral benchmark. It’s important to keep in mind that the exchange ratio may provide parties helpful insight on transactions involving all or part equity, but it won’t be beneficial for all cash deals.
The formula to calculate the ratio is as follows:
Exchange Ratio = Offer Price for Target’s Shares / Acquirer’s Share Price
Looking at the acquiring firm’s and the target or acquired firm’s share prices illustrates the exchange ratio. If the target firm has 30,000 shares outstanding and trades at $34.60, and the acquiring firm offers to pay a 20 percent takeover, it results in a share price of $41.52 per share. The acquiring firm’s share price currently trades at $23.50.
Putting the formula into practice, it’s as follows:
= $41.52 / $23.50
= 1.77
Based on the resulting Exchange Ratio of 1.77, the acquiring firm must issue 1.77 shares of its equity for each share of the target firm it wants to acquire.
For transactions with different proportions of cash and stock, the percentage of stock is what’s factored into the exchange ratio. Deals conducted with 100 percent stock provide the most value to an exchange ratio.
Real World Example
If an acquiring business offers the acquisition target two of its shares for a single share of the acquired company, the deal can take the following circumstances. Before the deal announcement, the purchasing company’s shares might be trading at $20, with the target company’s shares trading at $30. With a 2-to-1 exchange ratio, the purchaser is bidding $40 for the seller’s share at $30.
After the deal announcement, there’s usually a valuation difference between buyer and seller due to the time value of money and risks. Risks include potentially being blocked by regulators, shareholder rejection or changing economic conditions. One important consideration is that merger arbitration may occur by investors when they try to get ahead of a deal ultimately completing before the uncertainty is removed.
If the deal ultimately closes, and investors get two buyer shares in exchange for one seller share and the acquiring company’s share increases to $37 from $30, investors who bet against the buyer’s stock via short-selling will be rewarded a difference of $3 per share (2 shares from the acquiring company 2 X $20 = $40 minus the $37 single share price of the target company). Investors who close out their short position will see the difference from the seller’s price for a profit. This tactic is frequently executed by opportunistic investors who have no direct interest in owning the equity, but only for a trade.
While each deal is different, understanding the process is essential to break down the internal details for all interested merger and acquisition parties.
Understanding the Exchange Ratio
August 1, 2026 · Blog, General Business News, Uncategorized
⏱ 3 min read
With more than $57 trillion in mergers and acquisitions, according to the Institute for Mergers, Acquisitions & Alliances, understanding how the Exchange Ratio works is essential for businesses and investors to maximize these processes.
The ratio assesses how many shares the company that’s purchasing the takeover company must issue per share of the takeover business. Transactions that use shares for part or whole of the payment are able to leverage this integral benchmark. It’s important to keep in mind that the exchange ratio may provide parties helpful insight on transactions involving all or part equity, but it won’t be beneficial for all cash deals.
The formula to calculate the ratio is as follows:
Exchange Ratio = Offer Price for Target’s Shares / Acquirer’s Share Price
Looking at the acquiring firm’s and the target or acquired firm’s share prices illustrates the exchange ratio. If the target firm has 30,000 shares outstanding and trades at $34.60, and the acquiring firm offers to pay a 20 percent takeover, it results in a share price of $41.52 per share. The acquiring firm’s share price currently trades at $23.50.
Putting the formula into practice, it’s as follows:
= $41.52 / $23.50
= 1.77
Based on the resulting Exchange Ratio of 1.77, the acquiring firm must issue 1.77 shares of its equity for each share of the target firm it wants to acquire.
For transactions with different proportions of cash and stock, the percentage of stock is what’s factored into the exchange ratio. Deals conducted with 100 percent stock provide the most value to an exchange ratio.
Real World Example
If an acquiring business offers the acquisition target two of its shares for a single share of the acquired company, the deal can take the following circumstances. Before the deal announcement, the purchasing company’s shares might be trading at $20, with the target company’s shares trading at $30. With a 2-to-1 exchange ratio, the purchaser is bidding $40 for the seller’s share at $30.
After the deal announcement, there’s usually a valuation difference between buyer and seller due to the time value of money and risks. Risks include potentially being blocked by regulators, shareholder rejection or changing economic conditions. One important consideration is that merger arbitration may occur by investors when they try to get ahead of a deal ultimately completing before the uncertainty is removed.
If the deal ultimately closes, and investors get two buyer shares in exchange for one seller share and the acquiring company’s share increases to $37 from $30, investors who bet against the buyer’s stock via short-selling will be rewarded a difference of $3 per share (2 shares from the acquiring company 2 X $20 = $40 minus the $37 single share price of the target company). Investors who close out their short position will see the difference from the seller’s price for a profit. This tactic is frequently executed by opportunistic investors who have no direct interest in owning the equity, but only for a trade.
While each deal is different, understanding the process is essential to break down the internal details for all interested merger and acquisition parties.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 The purpose of estate planning is to distribute your assets to heirs in a formal, legal process. If you do not have any heirs to speak of, you might not feel the need to do this. However, your assets will go somewhere, so you may want to have control over that before the state steps in to decide for you.



 Anyone who has moved retirement money out of an old employer’s plan knows how frustrating it can be. Every administrator has their own forms. Timelines are all over the place. Paper checks show up weeks later with vague instructions. The whole thing should have been fixed a long time ago.
 Temps are dropping, the leaves are turning, and you know what that means: Fall is here, which is the best time to prepare your house for the chill that follows. But we all know that keeping warm takes energy and, yes, is costly. Here are a few easy ways to conserve.
 Continuing Appropriations and Extensions Act, 2027 (HR 6500) – This appropriations bill was finalized and passed by both the House and the Senate on Sept. 1. The act funds the fiscal year 2027 government budget through Dec. 11 at current levels. It was signed by the President on Sept. 2.
 With more than $57 trillion in mergers and acquisitions, according to the